

Successfully buying and selling at the same time in Hendricks County requires aligning your financing, listing timing, and closing dates across both transactions. With median days on market ranging from 9 days in peak months to 50-plus days in winter, preparation before you list is essential to avoid gaps or overlaps.
How do you time a home sale and purchase at the same time in Hendricks County?
The key is preparation before you list, not after. In Hendricks County, well-priced homes can go under contract in under two weeks during peak months, so buyers who aren’t ready on the purchase side can find themselves scrambling. Get pre-approved, scout your target area, and work with a title company experienced in back-to-back closings, that’s the framework that keeps both transactions moving together.
Most of the clients who come to me with this question are somewhere in the middle: they own a home they need to sell, they have a place they want to buy, and they’re not sure which move to make first. It feels like a puzzle with too many pieces. But it’s a solvable one, and I walk clients through it every year in this market.
Here’s what you need to understand about how Hendricks County’s market dynamics actually affect this coordination, and what the practical sequencing looks like.
What the Hendricks County Market Tells You About Timing
The first thing that surprises most sellers is how much the time of year matters here. According to MIBOR data tracked for Hendricks County, the median days on market for single-family homes in May 2026 was just 9 days. Compare that to January 2026, when the Indiana Association of REALTORS® monthly report showed an average of 53 days from listing to pending. That’s not a small difference. That’s the difference between a sale that closes in six weeks and one that drags into three months.
What that means for coordination: if you list in a slower month without your purchase side ready, you may actually have more time than you expect. If you list during peak activity and your home moves in under two weeks, you’d better already know where you’re going.
Inventory is tight. The same January 2026 REALTORS® report showed average daily inventory at 440 listings, well below the expected range of 575 to 635. By May 2026, active listings had dropped further to 358, down 10.5% year over year, while closed sales jumped 20.7%. That’s a market where sellers hold leverage and buyers face competition, which shapes every contingency conversation.
Recent local market data (trailing roughly 90 days as of August 2026) shows how the pace and price picture varies across the county’s major communities:
| Area | Median Sale Price | Median Days on Market |
|---|---|---|
| Plainfield | $358,000 | 42 |
| Avon | $365,000 | 47 |
| Brownsburg | $352,250 | 60 |
| Danville | $339,875 | 56 |
| Mooresville | $312,000 | 52 |
These are area-level medians. Your home’s actual value depends on condition, street, build year, and what’s closed nearby. But the directional story is clear: Brownsburg and Danville are sitting longer than Plainfield and Avon right now, and that affects how much cushion you have to find your next home after going under contract.
If you’re moving from Hendricks County toward West Indianapolis, the price picture shifts significantly. Redfin’s June 2026 data for West Side Indianapolis shows a median sale price of $209,427, up 5.1% year over year. That’s a meaningful gap compared to the $350,000 to $365,000 range across most of Hendricks County, which may give sellers moving in that direction more purchasing power on the buy side.
Sell First or Buy First?
This is the question I hear most. And the honest answer is: it depends on your risk tolerance, your financial position, and what the market looks like in your specific price range when you’re ready to move.
Selling first gives you certainty. You know your proceeds, your timeline, and your budget before you make an offer. The downside is that you may need temporary housing if the purchase takes longer than expected, which adds cost and stress.
Buying first removes the pressure of finding a home after your sale closes. The downside is carrying two mortgages if your current home doesn’t sell quickly, and in a tight-inventory environment, sellers may not accept a purchase offer that’s contingent on your home selling.
The middle path most of my clients take: get your home market-ready and your financing lined up simultaneously, list with a clear possession strategy (more on that below), and start seriously touring purchase options before you go active. In peak months, you won’t have weeks to search after going under contract. You need to be ready.
The Mechanics: How Both Closings Actually Come Together
In Indiana, closings are handled by a title company, not a closing attorney. That distinction matters here because the title company is the hub that coordinates both transactions when you’re buying and selling at the same time.
Here’s how the practical sequencing typically works:
Step 1: Pre-Approval and Purchase Scouting
Before your home hits the market, verify your financing on the buy side. Your lender needs to know whether you’re carrying your current mortgage through the purchase closing, using bridge financing, or structuring the deal around sale proceeds. Each path has different qualification requirements. Check with your lender early, not after you’re under contract on your sale.
Step 2: List with Possession Flexibility Built In
One of the most practical tools for coordination is post-closing occupancy. This is an agreement where you close on your sale but remain in the home for a defined period (often 30 to 60 days) while your purchase closes. It gives you a buffer if the two closing dates don’t align perfectly. Buyers sometimes accept this in exchange for a credit or rent payment; in a seller’s market, it’s often negotiable. This is worth discussing before you even accept an offer.
Step 3: Coordinate Closing Dates Through the Title Company
When both transactions are moving, the goal is often a same-day closing sequence: sell in the morning, buy in the afternoon, with funds from the sale flowing directly into the purchase. The title company manages that sequencing. It’s not guaranteed, and it requires both transactions to be on solid footing, but it’s a common local approach for clients who want to avoid bridge financing or a gap in housing.
The title company also handles the Indiana Sales Disclosure Form filing at closing. This form is required whenever a conveyance document is recorded in Indiana, and the county assessor must review and stamp it before it’s forwarded to the county auditor. It’s a standard step the title company manages, but if there are errors in the property data, parcel numbers, or legal description, it can delay recording. On a same-day close, that’s a problem. Accurate contract details from the start keep it from becoming one.
Indiana does not impose a state or county real estate transfer tax on the sale price, per Indiana Department of Local Government Finance guidance. Buyers and sellers still pay recording fees and other standard closing costs, but the absence of a transfer tax is a meaningful distinction from many other states and affects how closing costs are allocated. What those costs look like in your specific transaction is something to work through with your title company and your agent, not a number to estimate from a blog post.
Step 4: Keep Communication Moving
Two transactions mean two sets of deadlines, two lenders, two title orders, and two sets of inspections and appraisals. The place where coordinated moves fall apart is almost always communication gaps. I make it a point to stay in contact with both sides of a coordinated transaction so my clients aren’t the last to know when something shifts. You should never have to chase your agent for an update, especially when your housing situation is on the line.
For more on why communication is the backbone of a smooth transaction, I wrote about it directly here: Clear Communication in Hendricks County Real Estate.
And if you’re wondering whether the timing of your listing matters as much as I’m suggesting, this post on selling in fall in Hendricks County gets into the seasonal dynamics in more detail.
Your specific coordination plan depends on your home’s condition, your target price range, your timeline, and what the market looks like in the neighborhoods you’re targeting. That’s exactly the kind of conversation I have with clients before we make any moves.
If you’re thinking through a simultaneous sale and purchase, I’d also point you to this deeper look at buying and selling at the same time in Indiana for more on the financing and contingency mechanics.
See what past clients have said about working through these moves with me on Google, Zillow, and Realtor.com.
Frequently Asked Questions
How long does it usually take to sell a home in Hendricks County right now?
It depends heavily on the time of year and your price point. MIBOR data for May 2026 shows a median of 9 days on market for Hendricks County single-family homes, while January 2026 data from the Indiana Association of REALTORS® showed 53 days from listing to pending. Recent trailing data across specific communities ranges from 42 days in Plainfield to 60 days in Brownsburg. Pricing accurately from the start is the single biggest factor in where your home lands in that range.
Is it better to sell my Hendricks County home first or buy first?
Selling first gives you financial certainty but may require temporary housing. Buying first removes the search pressure but carries the risk of two mortgage payments if your sale takes time. In Hendricks County’s current tight-inventory environment, many sellers find a middle path: get market-ready and start touring purchase options before listing, so you’re not caught flat-footed when your home goes under contract quickly. Your financing situation and risk tolerance should drive the decision.
How can I time my closing dates so I don’t end up with two mortgages or no place to live?
The most common local solution is a same-day closing sequence coordinated through the title company, where proceeds from your morning sale fund your afternoon purchase. Post-closing occupancy agreements can also give you a buffer if the dates don’t align perfectly. Both approaches require solid contracts on both sides and advance coordination with your agent, lender, and title company well before closing day.
What does a title company do in a Hendricks County home sale, and how do they coordinate a sale and purchase?
The title company runs the title search, prepares closing documents, manages funds disbursement, and handles recording with the county recorder, including the required Indiana Sales Disclosure Form. When you’re buying and selling simultaneously, the title company sequences the closings so proceeds from your sale can flow into your purchase. They’re the operational hub that makes same-day coordinated closings possible.
Does Indiana have a real estate transfer tax that affects my closing costs in Hendricks County?
Indiana does not impose a state or county real estate transfer tax on the sale price, which sets it apart from many other states. Buyers and sellers still pay recording fees and standard closing costs, but there’s no statutory transfer tax percentage applied to the transaction. The exact allocation of costs in your specific deal is negotiable between the parties and should be confirmed in your contract and with your title company.
Coordinating a sale and purchase in Hendricks County is manageable when you understand the market’s seasonal pace, build possession flexibility into your sale, and work with a title company experienced in back-to-back closings. The details of your specific situation, your timeline, and your target neighborhoods are what determine the right sequence for you.
I’d be glad to walk through your specific situation and put together a plan that accounts for both sides of your move. Request a free home valuation and consultation here.
Equal Housing Opportunity. René Hauck is a Broker with RE/MAX Advanced Realty, licensed in Indiana since 2014, regulated by the Indiana Real Estate Commission. This article is general information only and is not legal, tax, or financial advice. Confirm your specific costs and transaction details with your title company, tax advisor, or lender.
- About the Author
- Latest Posts
- Free Guides
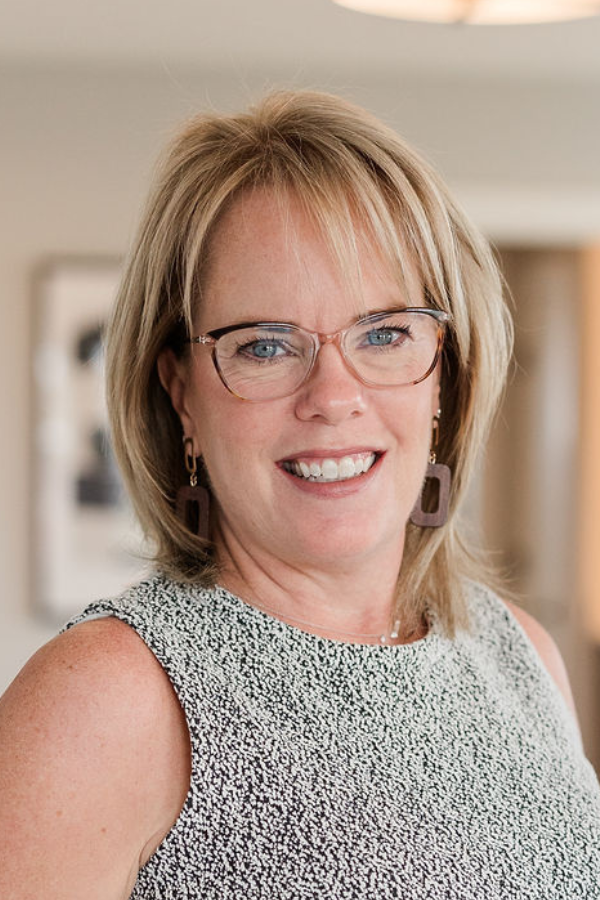
Selling or buying a home can feel overwhelming. I guide you through each step so you always know what’s next, and you’ll have peace of mind knowing you chose the right agent to navigate it.
René Hauck is a REALTOR® with RE/MAX Advanced Realty in Plainfield, Indiana, holding the Seniors Real Estate Specialist® (SRES®) designation and Pricing Strategy Advisor (PSA) certification. With 240+ closings and $51M+ in volume across Hendricks County and West Indianapolis, she specializes in downsizing, life-transition moves, and helping sellers navigate the market with confidence. Read her client reviews on Google, Zillow, and Realtor.com or reach her at rene@indyhomepros.com.
Curious what your home is worth? What’s my home worth? · Call or text (317) 987-7068.
